
Data-driven materiality for Corporate Reporters
Workshop purpose
We gathered a number of corporate reporters, together with assurance providers, institutional investors and data platforms, at UCL’s Centre for Sustainable Business in September 2026. This was the second industry workshop on a data-driven approach to financial materiality for sustainability matters. It followed an initial workshop in May at Brunel University and a series of proof-of-concepts completed over the summer with reporters, investors, assurers and other stakeholders.
The objective was to test whether the proposed methodology is understandable, robust, and useful across different use cases, and whether it could support a standard way of calculating financial materiality that is explainable, repeatable and objective. The workshop was conducted under Chatham House rules.
Key Insights and Learnings
There are 6 discrete use cases: corporate reporter, SME reporter, assurance provider, institutional investor, financial data provider, strategic advisory
Better explanation of the framework required
Link material topics to reportable IROs
Predictive analysis for investors, but also for reporters
Apply the approach to SMEs and private companies
Structure
This note focuses on the ‘Corporate Reporter’ use case and is structured as follows:
The three-body framework
Proof-of-concept insights
Reporter perspective
Workshop outcomes
Next steps
1. The three-body framework
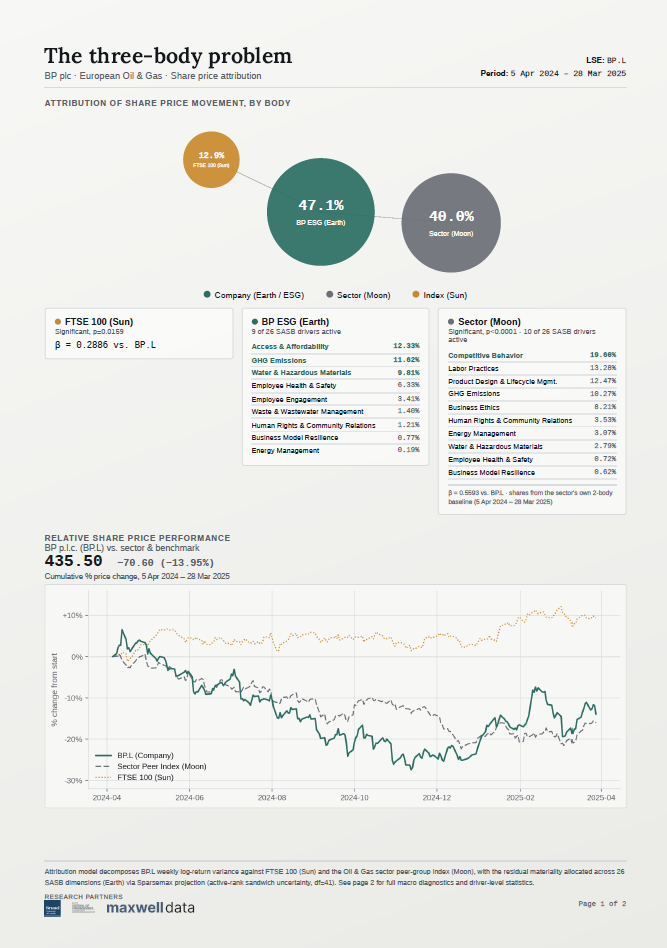
The Earth: the company – the listed entity whose weekly share-price return is being examined.
The Moon: the peer group – the industry whose movement exerts a strong influence on the company.
The Sun: the index – the wider market benchmark against which company and industry effects are placed in context.
The analogy reflects the classical three-body problem. In the financial-materiality model, a company cannot be interpreted in isolation: a movement may be specific to the entity, common to its industry, or part of a wider market movement.
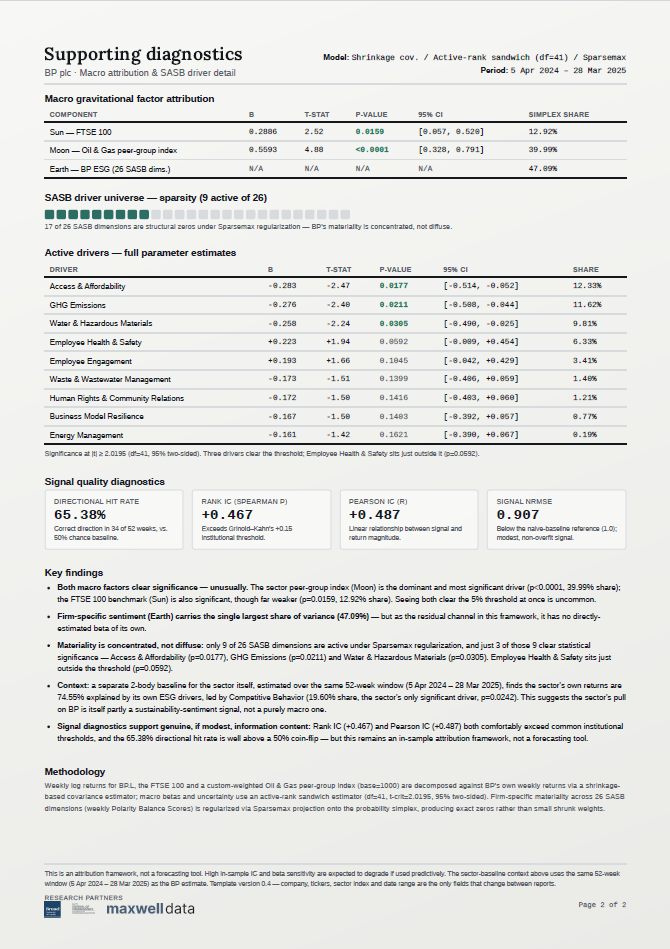
The model uses the SASB topic taxonomy to organize sustainability drivers. It compares weekly returns with external sentiment associated with those topics, then allocates relative importance across the company, peer group, index, and active sustainability drivers. Non-active drivers are reduced to zero, allowing attention to focus on the smaller set that contributes to the model for the period examined.
Source: Maxwell Data
What the model measures, and what it does not
It measures association – the analysis identifies sustainability sentiment that moves with weekly stock returns after industry and index effects have been considered.
It is relative – the allocations show which factors are more important than others within the model. They should not be read as an exact statement that a particular percentage of total return was caused by one topic.
It is retrospective – the proof-of-concepts assess historical alignment. They do not yet predict future returns.
It distinguishes activity from statistical significance – a driver may remain active in the allocation even when its conventional p-value does not pass a particular threshold. The two diagnostics answer different questions and should be displayed separately.
It is not the whole share-price model – earnings, pipeline, operations, capital allocation, innovation, macroeconomics, and many other factors also affect valuation. The current work isolates a sustainability-related component.
Source: Maxwell Data
External sentiment data
The analysis intentionally uses information available in the external market rather than content produced directly by the company. Company annual and sustainability reports are excluded from the sentiment input so that the result can provide an independent comparison with what the company says about itself.
Sources – news and financial media, specialist trade publications, blogs, forums and selected social-media sources. The strongest industry-specific signal was often found in specialist trade publications. Twitter was not used at the time because of data-quality concerns, and broadcast media was not captured directly.
Company material – company-owned webpages and reports are filtered out as inputs, although external discussion prompted by a company announcement is captured.
Authenticity – the team monitors short-lived accounts, bots, duplicated content, public-relations material, and other indications of manufactured conversation. Source selection remains an ongoing control rather than a solved problem.
Language and geography – local-language material is important because English-language discussion of a non-UK company can be global or less representative. At the time of the workshop, coverage centered on the UK, Europe, and the United States, with more limited coverage elsewhere and no complete Mandarin-language dataset.
Classification – machine reading uses a contextual library of approximately 77,000 keywords and phrases to assign relevant items to SASB topics and classify sentiment as positive, neutral, or negative. Thresholds are set conservatively to reduce false positives.
Persistence – sentiment is not treated as disappearing the day after publication. A decay factor recognizes that information can continue to influence market understanding over subsequent weeks.
Participants emphasized that this is sentiment about matters such as greenhouse-gas emissions, not a direct measurement of the emissions themselves. The model assumes that underlying reported facts are broadly accurate and analyses how the wider market responds to, interprets, or questions them.
2.Proof-of-concept portfolio insights
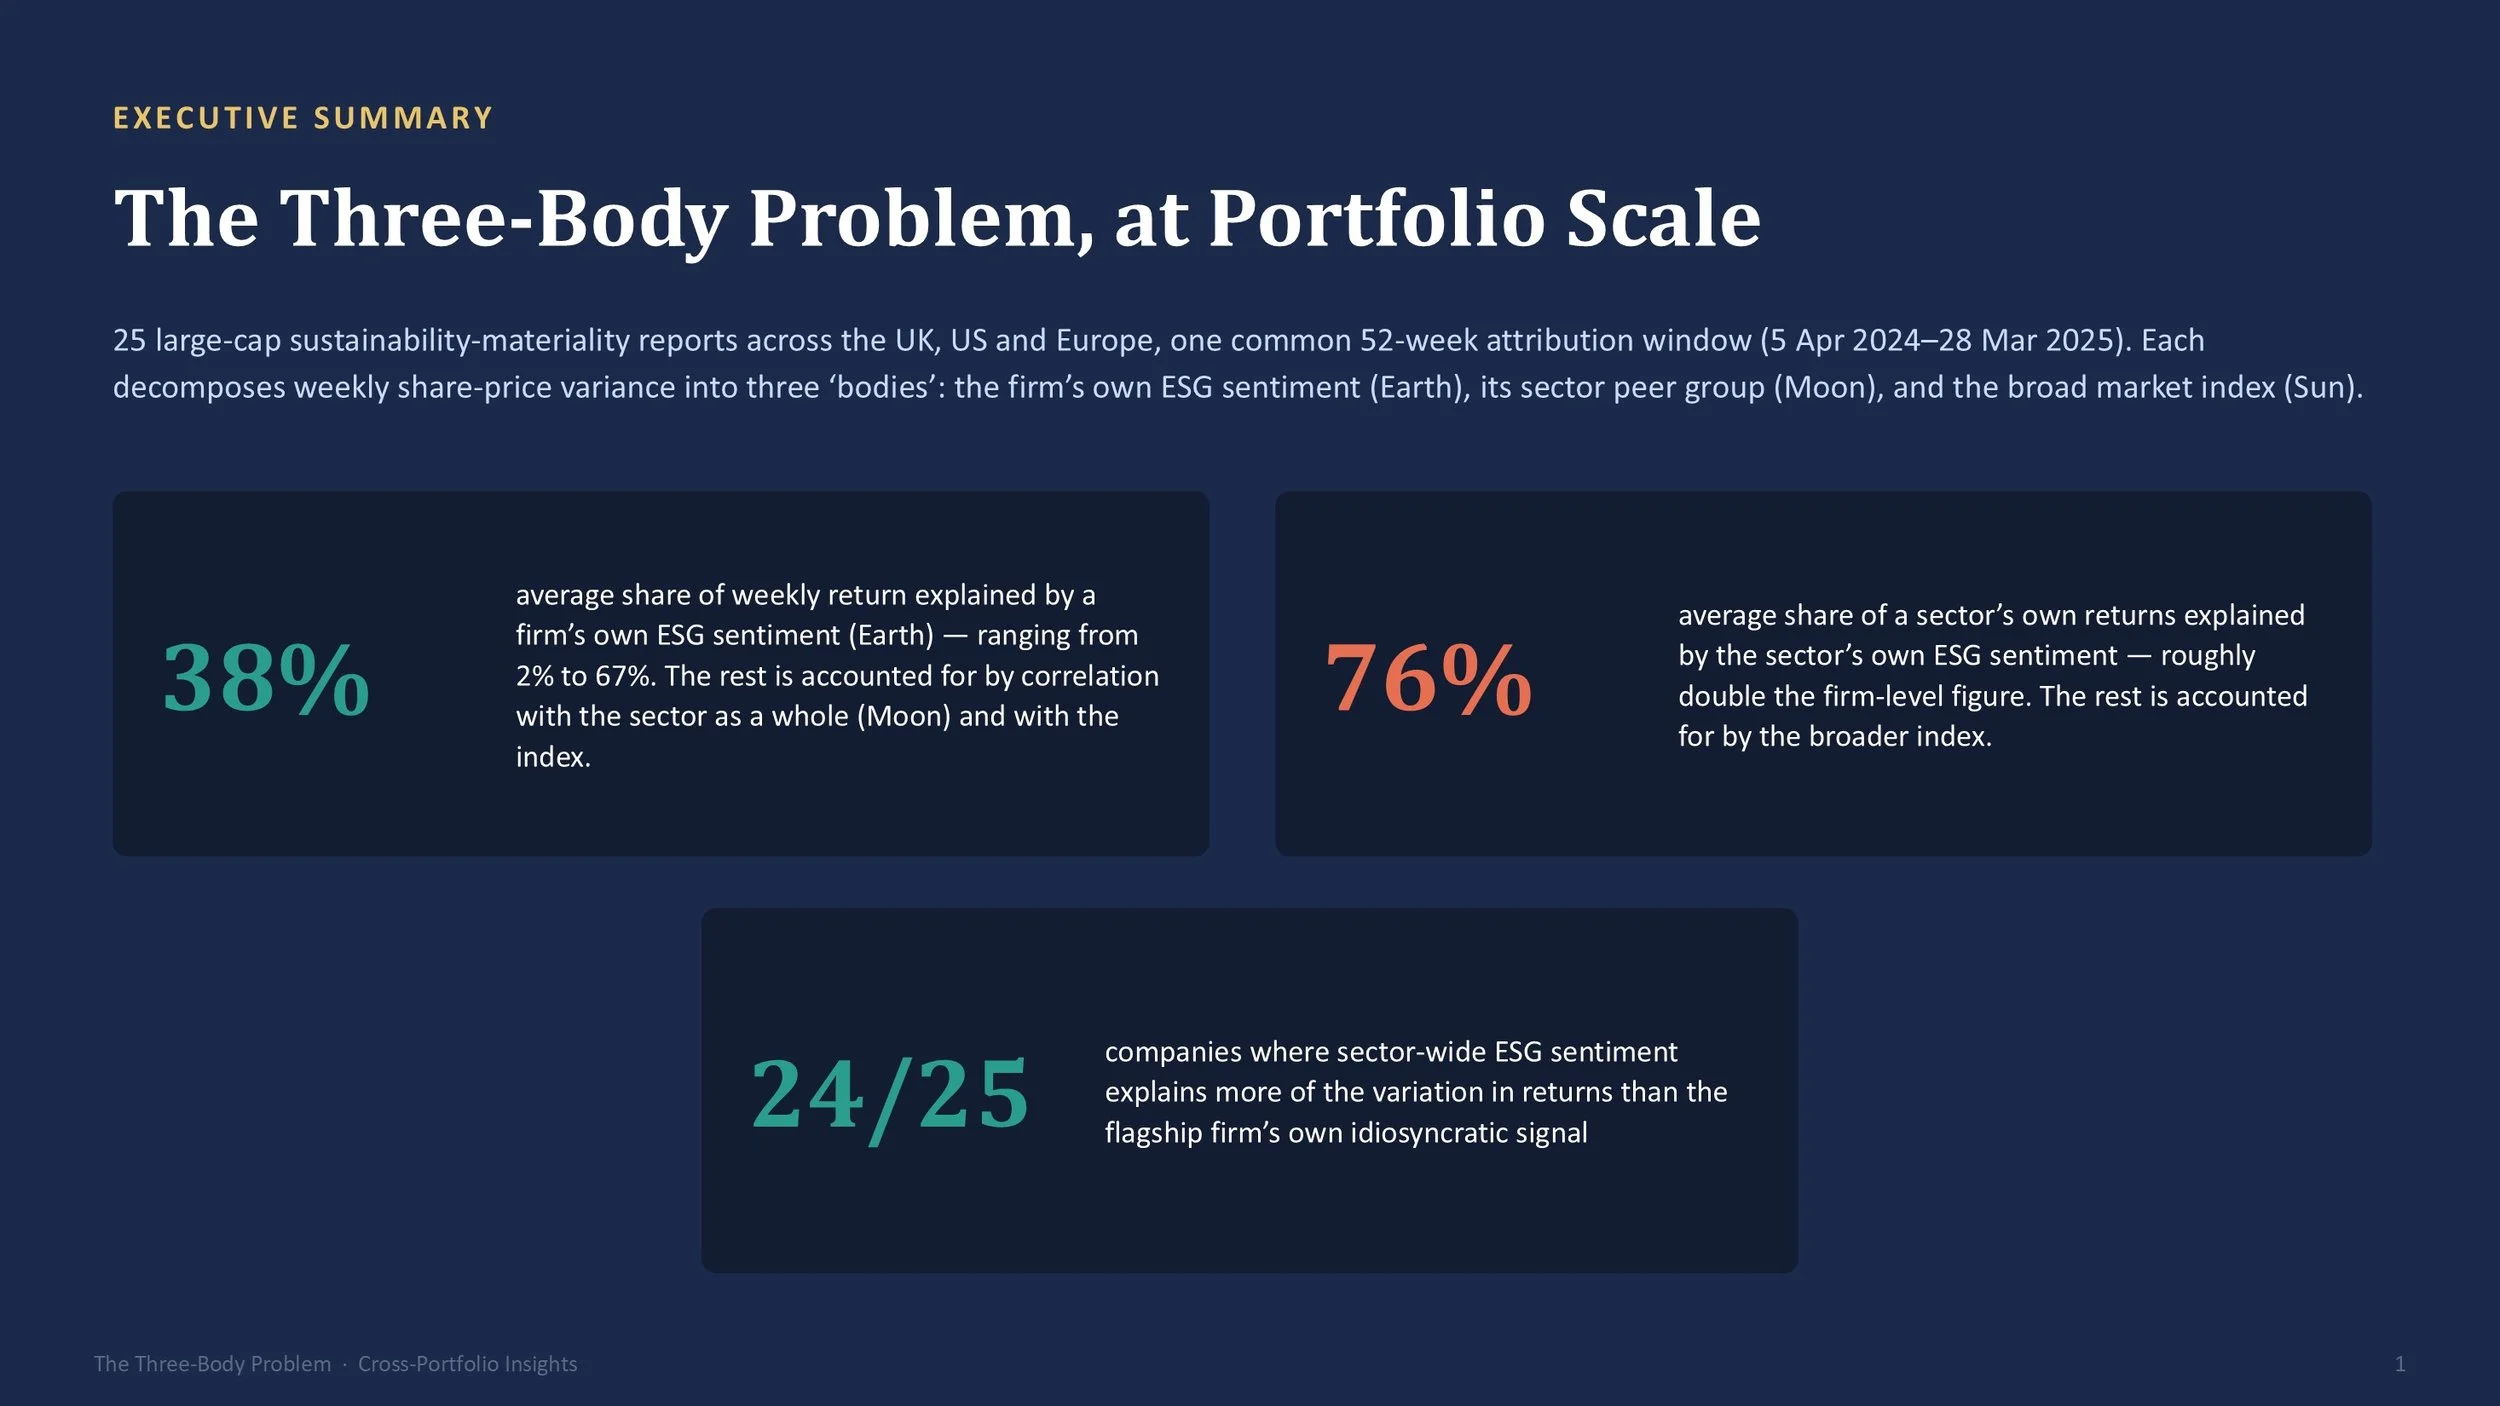
The presentation summarized analysis across a portfolio of 25 listed companies spanning the 11 SASB industries. The broader working database contains around 1,500 companies, principally in the UK, Europe, and the United States. The figures were presented as early evidence from a developing model rather than universal conclusions.
Company-specific movement remains material – on average, approximately 38% of weekly return variation in the initial portfolio was described as unique to the entity, although results varied substantially between companies.
The industry effect was often stronger – for 24 of the 25 companies examined, industry-wide sustainability sentiment explained more variation than the firm's own idiosyncratic sustainability signal.
Recurring firm-level topics – supply-chain management, physical impacts of climate change and customer privacy appeared repeatedly among company-specific drivers.
Recurring industry-level topics – ecological impacts, employee engagement, supply-chain management and labour practices appeared repeatedly at industry level
Divergence can be informative – negative company-specific sentiment can outweigh a rising industry or market. A widening difference between company and peer-group sentiment may therefore provide an early warning for reporters, investors, lenders, or insurers.
Directional hit rate is a diagnostic – the team compared the sign of the sentiment signal with the sign of weekly return. A 50% result would be equivalent to chance in a two-direction test; performance above that level is evidence of alignment, not a forecast.
Source: Maxwell Data
Peer-group construction
The choice of peer group emerged as one of the most important methodological decisions. Very small groups chosen by a company produced unstable or extreme results, while broad exchange-traded funds could be too smoothed to reveal useful industry dynamics. The proof-of-concepts suggested that a group of roughly 10 to 50 companies, with about 30 as a practical center point, created a more robust evidence base.
A further suggestion was to test whether peer groups could be derived from the similarity of active drivers rather than only from a pre-existing industry classification. This could reveal economically relevant relationships that do not map neatly onto conventional industry boundaries.
3. Reporter perspective
Reporters generally saw the output as an additional evidence source rather than a complete materiality assessment. One proposed use was to map the company's impacts, risks, and opportunities to SASB topics and then compare the company's double materiality assessment with the independent external signal.
Completeness check – identify a material topic appearing in external data but missing from the company's assessment, or test whether an internally selected topic has visible market support.
Starting point or cross-check – some participants would use the model at the beginning to narrow the field; others, particularly smaller listed companies, preferred to complete their own assessment first and use the output as a validation layer.
Board and CFO engagement – a connection to market evidence could help explain why a topic warrants governance attention, but boards would still expect scenario analysis, sensitivity analysis, business evidence and a clear account of limitations.
Risks and opportunities – the sign of the relationship may help distinguish a potential downside risk from an upside opportunity. The broad topic must then be disaggregated into specific impacts, risks and opportunities before a reporting decision is made.
Dynamic monitoring – the analysis could be rerun during or between reporting cycles to identify changes in external attention and company-to-industry divergence rather than relying on a static annual assessment.
Participants welcomed a more objective foundation because many materiality assessments remain heavily dependent on workshops, small stakeholder samples or last year's conclusions. However, they cautioned against replacing one form of box-ticking with another. Internal knowledge, strategy, stakeholder impact and low-frequency high-severity risk remain necessary inputs.
Investment mosaic – combine the external sentiment signal with analyst notes, reported data, engagement, scenario analysis and fundamental research. No single input should be treated as the complete answer.
Long-term mandate – the relevance of a sustainability signal depends partly on the investor's time horizon and thesis. A short-term trader and a long-term asset owner may interpret the same evidence differently.
Participants warned against describing correlation as prediction or causation. They also noted that investment and ratings processes increasingly use automated screening. Clear definitions and machine-readable consistency therefore matter, but binary automated outputs can create new errors when company language does not match a model's search logic.
Business use cases beyond reporting
Enterprise risk – risk teams could use dynamic, market-linked evidence to test whether sustainability-related issues should enter reputation, operational or strategic risk discussions.
Reputation – reputation-risk committees could compare what the organisation believes matters with what external audiences are discussing and identify gaps.
Tendering and social value – one participant described social value as 20% of a tender score. Where it contributes materially to bid outcomes, strong performance can affect pipeline and future revenue, while external evidence may help demonstrate differentiation from competitors.
Marketing and communications – the signal can show which narratives exist in the market and where communication is disconnected from material issues. It should inform communication, not be used to manufacture, or manipulate sentiment.
Internal engagement – linking a topic to business performance may help overcome scepticism where the language of ESG or sustainability causes immediate resistance.
Product development – data platforms may be able to offer the factor outputs as part of a wider analytical product, provided the methodology and coverage can be standardised.
Language, integration and the limits of the ESG label
Several participants argued that sustainability has become too separate from ordinary business management. Energy use, health and safety, workforce capability, community relationships, supply chains and operational efficiency existed long before they were labelled ESG. When the label creates resistance, the same issues may be discussed more effectively in the language of cost, risk, talent, pipeline, resilience, or license to operate.
This led to a broader challenge: financial materiality is not limited to sustainability topics. Innovation, systems, operating efficiency, talent attraction, capital allocation, geopolitical risk and earnings can be more important to a company's success or failure. The current model should therefore be presented as a sustainability-related subset of total financial materiality, not as a complete explanation of corporate value.
A future output could display the sustainability allocation alongside the residual and conventional business drivers. Participants described a longer-term ambition in which users could see, at a high level, the relative contribution of earnings, pipeline, operations, innovation, industry conditions and sustainability-related factors without confusing correlation with a complete causal model.
4. Workshop Outcomes
The workshop supported the direction of a data-driven approach to financial materiality, provided it remains transparent about what it measures and what it leaves out. The three-body framework offers a useful way to distinguish the company from its industry and the wider market, while external sentiment supplies an independent perspective on which sustainability matters are being reflected in market behaviour.
The strongest future proposition is not a single ESG score. It is an explainable, repeatable baseline that shows where company-specific and industry-wide signals differ, connects those signals to specific reporting and investment questions, and sits inside a broader understanding of enterprise value.
5. Next Steps
1. Simplify the presentation and distinguish clearly between active drivers, statistical significance, relative allocation, and absolute explanatory power.
2. Include 1, 3 and 5-year time horizons to speak to short-, medium- and long-term time horizons.
3. Allow users to inspect the source stories, volume, language, and sentiment underlying each topic so that outputs can be challenged and assured.
4. Develop transparent rules for peer-group selection, including minimum viable group size and controls for dominant companies.
5. Validate the signal against analyst research, market-data platforms, ratings, and subsequent performance to test whether it is leading, coincident or lagging.
6. Design practical workflows for reporters, including topic-to-IRO mapping, peer challenge and board reporting.
7. Show the sustainability-related component within a wider account of financial materiality, including residual and conventional business drivers.